
How to Save on Car Insurance Renewals Without Cutting Cover
Renewal prices often rise even without a claim. Comparing quotes early, correcting details, and adjusting voluntary excess can cut the bill without losing protection.
293 stories published in 2026
Renewal prices often rise even without a claim. Comparing quotes early, correcting details, and adjusting voluntary excess can cut the bill without losing protection.
A red sale badge does not mean a bargain. Fake sales inflate the original price, hide exclusions, or push a product you never wanted.

You can track spending well without giving an app your bank login. Manual-entry apps protect privacy and force you to notice every purchase.
A holiday fund on a tight budget is a weekly habit, not a windfall. Small automatic transfers, a clear target, and early bookings make six months enough.
Switching phone plans can save a noticeable amount, but only if the new plan fits your real data use, coverage, and contract end date.
Impulse buying is engineered by one-click checkout and endless feeds. Practical friction, waiting rules and a clear list beat willpower alone.

Most budgets fail because they are too strict or too complicated. A budget that sticks is simple, realistic and built around your actual spending.
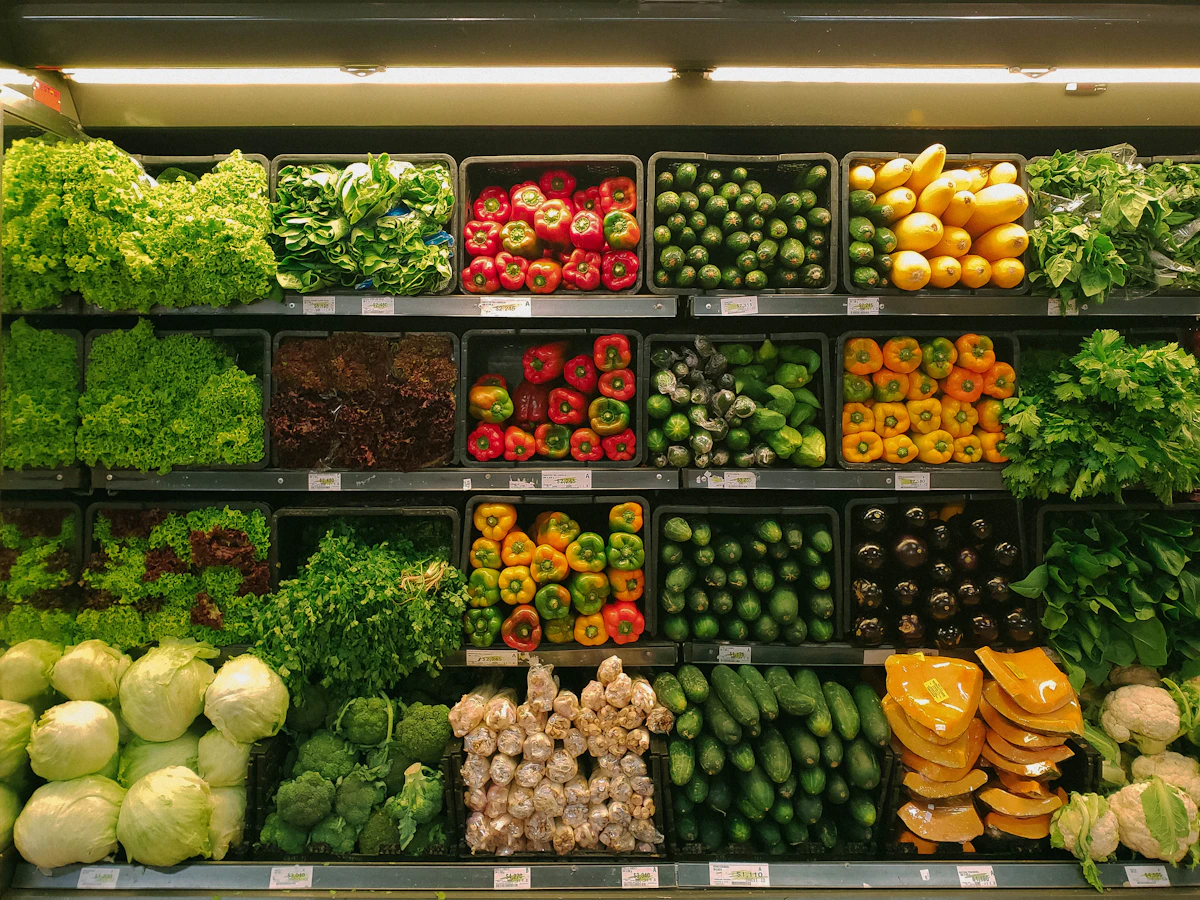
Grocery bills are one of the easiest places to save without sacrifice. Meal planning, smart shopping habits and a few simple swaps can cut costs while keeping meals tasty.

Snowball and avalanche are the two most popular debt payoff methods. One builds motivation with quick wins, the other saves money on interest. Here is how to choose.
An emergency fund feels impossible when money is tight, but it is built the same way as any big goal: with small, automatic amounts that add up over time.
Free gift cards are real, but so are the scams around them. These legitimate methods earn small rewards for your time, with no fees and no false promises.
Your credit score is built on habits, not spending. Paying on time, keeping balances low and avoiding common mistakes can raise it steadily at no cost.
Cashback apps and cashback cards both return money on spending, but they work differently. Compare fees, effort and real returns to see which fits your habits.
Subscriptions are small individually but add up fast. A regular audit, a simple rule for new sign-ups and a few cancellations can free up real money every month.
The 50/30/20 rule splits your income into needs, wants and savings. A worked example shows exactly how it looks on a real monthly income.
Your bills are often negotiable, even when providers pretend they are not. A short, polite call armed with competitor prices can cut your monthly costs.

Most budgets fail because they are vague: spend less, save more, be careful. Zero-based budgeting works differently, and it works precisely because it is specific. Before the month starts, you assign every dollar of your
Surprise bills are not actually surprises: car insurance renews every year, holidays arrive every December, and appliances eventually break. Yet these predictable costs wreck budgets month after month, because they are n

Online shopping is engineered to make you buy without thinking: one-click checkout, limited-time banners, personalised ads, and 'only two left' warnings. Impulse buying is not a character flaw; it is a response to a syst

Saving what is left at the end of the month rarely works, because by month's end there is usually nothing left. Pay yourself first reverses the order: the moment income arrives, a fixed amount moves to savings before any

Buy now, pay later feels harmless: split a purchase into four easy payments, no interest, no paperwork. But when several plans overlap, those easy payments stack into a serious monthly burden, and missed instalments can

Every January, millions of people start the year paying off December. Christmas spending feels unavoidable, but the debt that follows it is not: it is simply the result of treating a predictable annual expense as a surpr
When multiple debts with high interest start to feel unmanageable, two options come up again and again: a debt consolidation loan and a balance transfer card. Both can lower your costs, but they work very differently, an
Your credit report quietly shapes major financial decisions: loan approvals, interest rates, rental applications, and sometimes even job offers. Yet errors on credit reports are surprisingly common, from accounts that ar